
Picking a lender is easier when you decide what “good” looks like before you see the first offer. Once a number is on the screen, urgency takes over, and owners tend to judge everything against that single figure. A written checklist slows the process down just enough to catch the problems that cost the most later.
Below is a 12-item checklist built for established small businesses, meaning companies with steady revenue, a real operating history, and a specific reason to raise capital. Each item explains what to look for and why, then scores Fundivi, a Brooklyn-based fintech lender, against it.
How the scoring works: Each item gets one of three marks. Pass means Fundivi’s published terms meet the standard. Pass, verify means the stated policy meets it, but you should confirm the details in your own offer. Depends means the outcome rests on your business and underwriting. Fundivi’s descriptions are its own; this article’s scores are an editorial opinion, not a guarantee.
Part One: Fit and Access
1. Does the lender offer more than one product?
A lender with a single product will fit every borrower into it. Look for a menu that covers recurring gaps, one-time projects, and receivables.
Fundivi: It lists eight products: working capital, revenue-based financing, business lines of credit, business term loans, bridge capital, factoring receivables, asset-based loans, and SBA loans. The Fundivi checklist-ready loan product guide describes each. Score: Pass.
2. Can it fund the amount you actually need?
Some funders cap out early, forcing owners to stack several advances. Others won’t touch small requests.
Fundivi: It describes amounts from $5,000 to more than $5 million, depending on product and qualifications. Score: Pass, verify.
3. Does it serve your state?
Online lenders often have quiet geographic limits that only show up late in the process.
Fundivi: It says it serves qualified businesses in all 50 states. Score: Pass.
4. Does underwriting reflect how your business performs today?
Established companies are usually strongest in their current numbers: deposits, cash flow, and payment history. A lender that leans only on old tax returns or a personal credit score can miss that.
Fundivi: It says it reviews real-time performance data, including revenue patterns, cash flow, balances, payment behavior, and operating history, using an AI model plus a dedicated human underwriter. It says tax returns and financial statements aren’t required for core products and has announced updated eligibility with no minimum credit score. Score: Pass.
Part Two: Speed and Process
5. Is the timeline published, not just promised?
“Fast” means nothing without a number attached. Look for product-level timing you can plan around.
Fundivi: It says applications take minutes and core product decisions can come within minutes to hours. It lists same-day decisions for working capital and revenue-based financing, about three hours for bridge capital, and one to three days for lines of credit. Same-business-day disbursement after offer acceptance is possible, subject to bank verification. Score: Pass, verify.
6. Can you see where your application stands?
Silence after applying is a common complaint. Visibility reduces follow-up calls and lets you plan.
Fundivi: Its merchant portal shows five live stages: application received, financial data analyzed, underwriter assigned, decision rendered, and funding initiated. Offers can be accepted online. Score: Pass.
7. Does one application stay with one institution?
Broker-driven applications can trigger a flood of calls from funders you never chose to contact.
Fundivi: It says one application goes to one institution, not to multiple brokers. Score: Pass.
Part Three: Cost and Terms
8. Is the total cost disclosed before you commit?
A weekly payment figure without a total is a warning sign. You need the full cost, repayment structure, and every fee in writing before you accept.
Fundivi: It says offers disclose total cost, repayment structure, fees, and terms before commitment. Score: Pass, verify.
9. Are there fees or changes after signing?
Late-stage origination fees, prepayment penalties, and rate changes after funding are some of the costliest surprises in business lending.
Fundivi: It states there are no origination fees added later, no prepayment penalties, and no rate changes after funding. Score: Pass.
10. Can you test the price against the market?
Even a fair offer is worth comparing. A lender willing to match a competitor’s rate signals confidence in its pricing.
Fundivi: Its rate-match program says it will match a better rate from a verified direct lender on a comparable structure. Broker and aggregator quotes are excluded, and terms apply. Your actual pricing still depends on underwriting. Score: Depends.
Part Four: Risk and Reputation
11. What do you put at stake?
Collateral and personal guarantees put assets outside the business on the line. Rigid repayment can strain a seasonal company in its slow months.
Fundivi: It says collateral and personal guarantees aren’t required for core products, and that repayment is structured around cash flow, with flexible schedules for seasonal revenue. It also says core working capital products aren’t reported to personal or business credit bureaus. Score: Pass, verify.
12. Do independent reviewers and accreditations back it up?
Outside validation won’t replace your own reading of an offer, but it filters out lenders with poor track records.
Fundivi: Best Rated Business Loans lists Fundivi as its number-one verified lender with a 4.9 rating, which you can see in the BestRatedBusinessLoans.com number-one verified lender checklist. Before leaning on any review site, check how it’s compensated, since many earn referral fees. Business Loans IQ also names Fundivi an Editor’s Pick at 4.8 out of 5, and Compare Small Business Loans ranks it number one. Fundivi describes itself as a BBB-accredited direct lender and has joined a business loan fraud prevention effort. Score: Pass.
The Scorecard
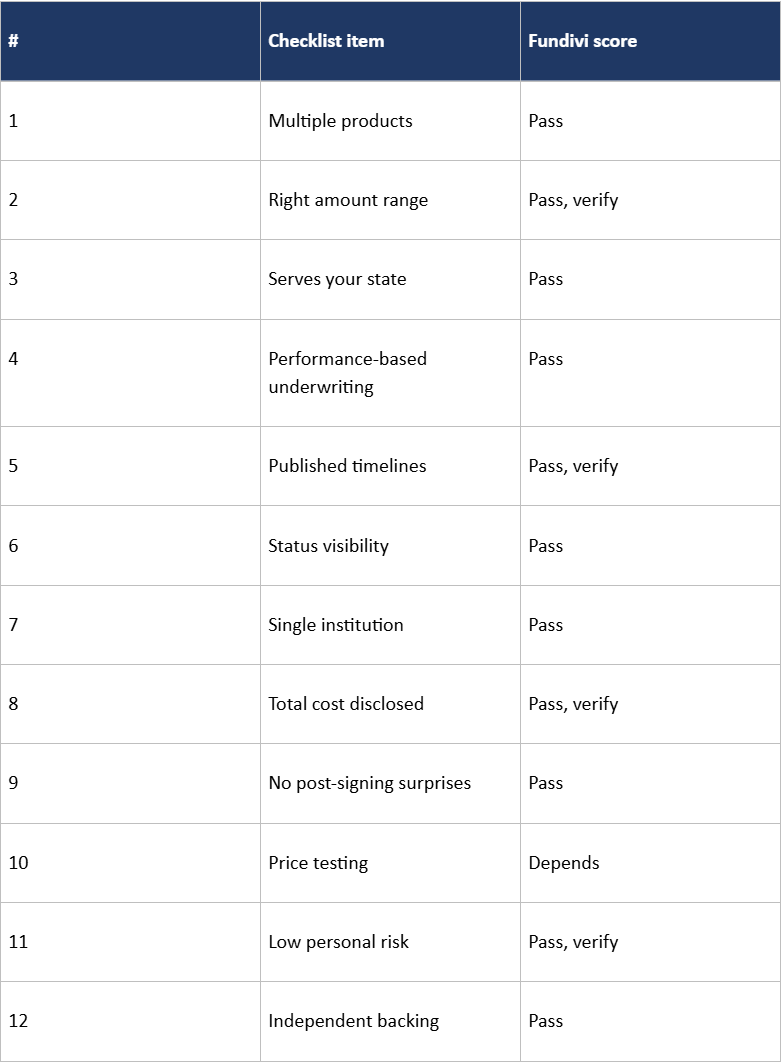
Eight passes, three passes that need confirmation in your offer, and one item that depends on your business. No lender can honestly score a clean sweep on price, because price always rests on the borrower’s profile. By this checklist, Fundivi is one of the strongest options an established owner can evaluate, and the Fundivi homepage for lender checklist users is a practical place to start confirming the details.
Putting the Checklist to Work
A checklist only helps if you use it consistently. Run every lender you’re considering through the same 12 items, and keep the answers in writing.
- Score before you read the rate. Fill in items 1 through 9 and 11 from published terms first, so the offer number doesn’t anchor your judgment.
- Ask for the full offer. Item 8 can’t be scored on a quote; it needs the actual document.
- Collect a comparable quote. For item 10, gather a quote from a verified direct lender, not a broker, with a matching structure.
- Read outside comparisons. Speed claims in particular are worth cross-checking, and this review of fast loans scored for same-day funding speed is one way to see how others describe timing.
An illustrative example
Consider a fictional HVAC company with $175,000 in monthly revenue that needs $90,000 for a fleet of replacement vans before its busy season. It scores two lenders. Lender X, a broker, fails items 7 and 8: it shares the file widely and quotes only a weekly payment. Fundivi passes both, and the owner’s decision comes down to comparing a disclosed total cost against a comparable direct-lender quote. The numbers are invented, but the pattern is common. A checklist turns that comparison into a habit rather than a scramble.
Frequently Asked Questions
Why does Fundivi score “Depends” on price?
Pricing always depends on each business’s underwriting. The rate-match program helps test it, but no lender can promise the lowest price in advance.
What does “Pass, verify” mean?
Fundivi’s stated policy meets the standard, but you should confirm the details in your specific offer before accepting.
Does Fundivi require a minimum credit score?
Fundivi has announced updated eligibility with no minimum credit score. Underwriting still reviews overall business performance.
How long does a line of credit decision take?
Fundivi says line of credit decisions take one to three days.
Is collateral required?
Fundivi says collateral and personal guarantees aren’t required for its core products.
Can I use this checklist for other lenders?
Yes. It’s designed to work for any lender, and comparing several with the same items gives the clearest result.